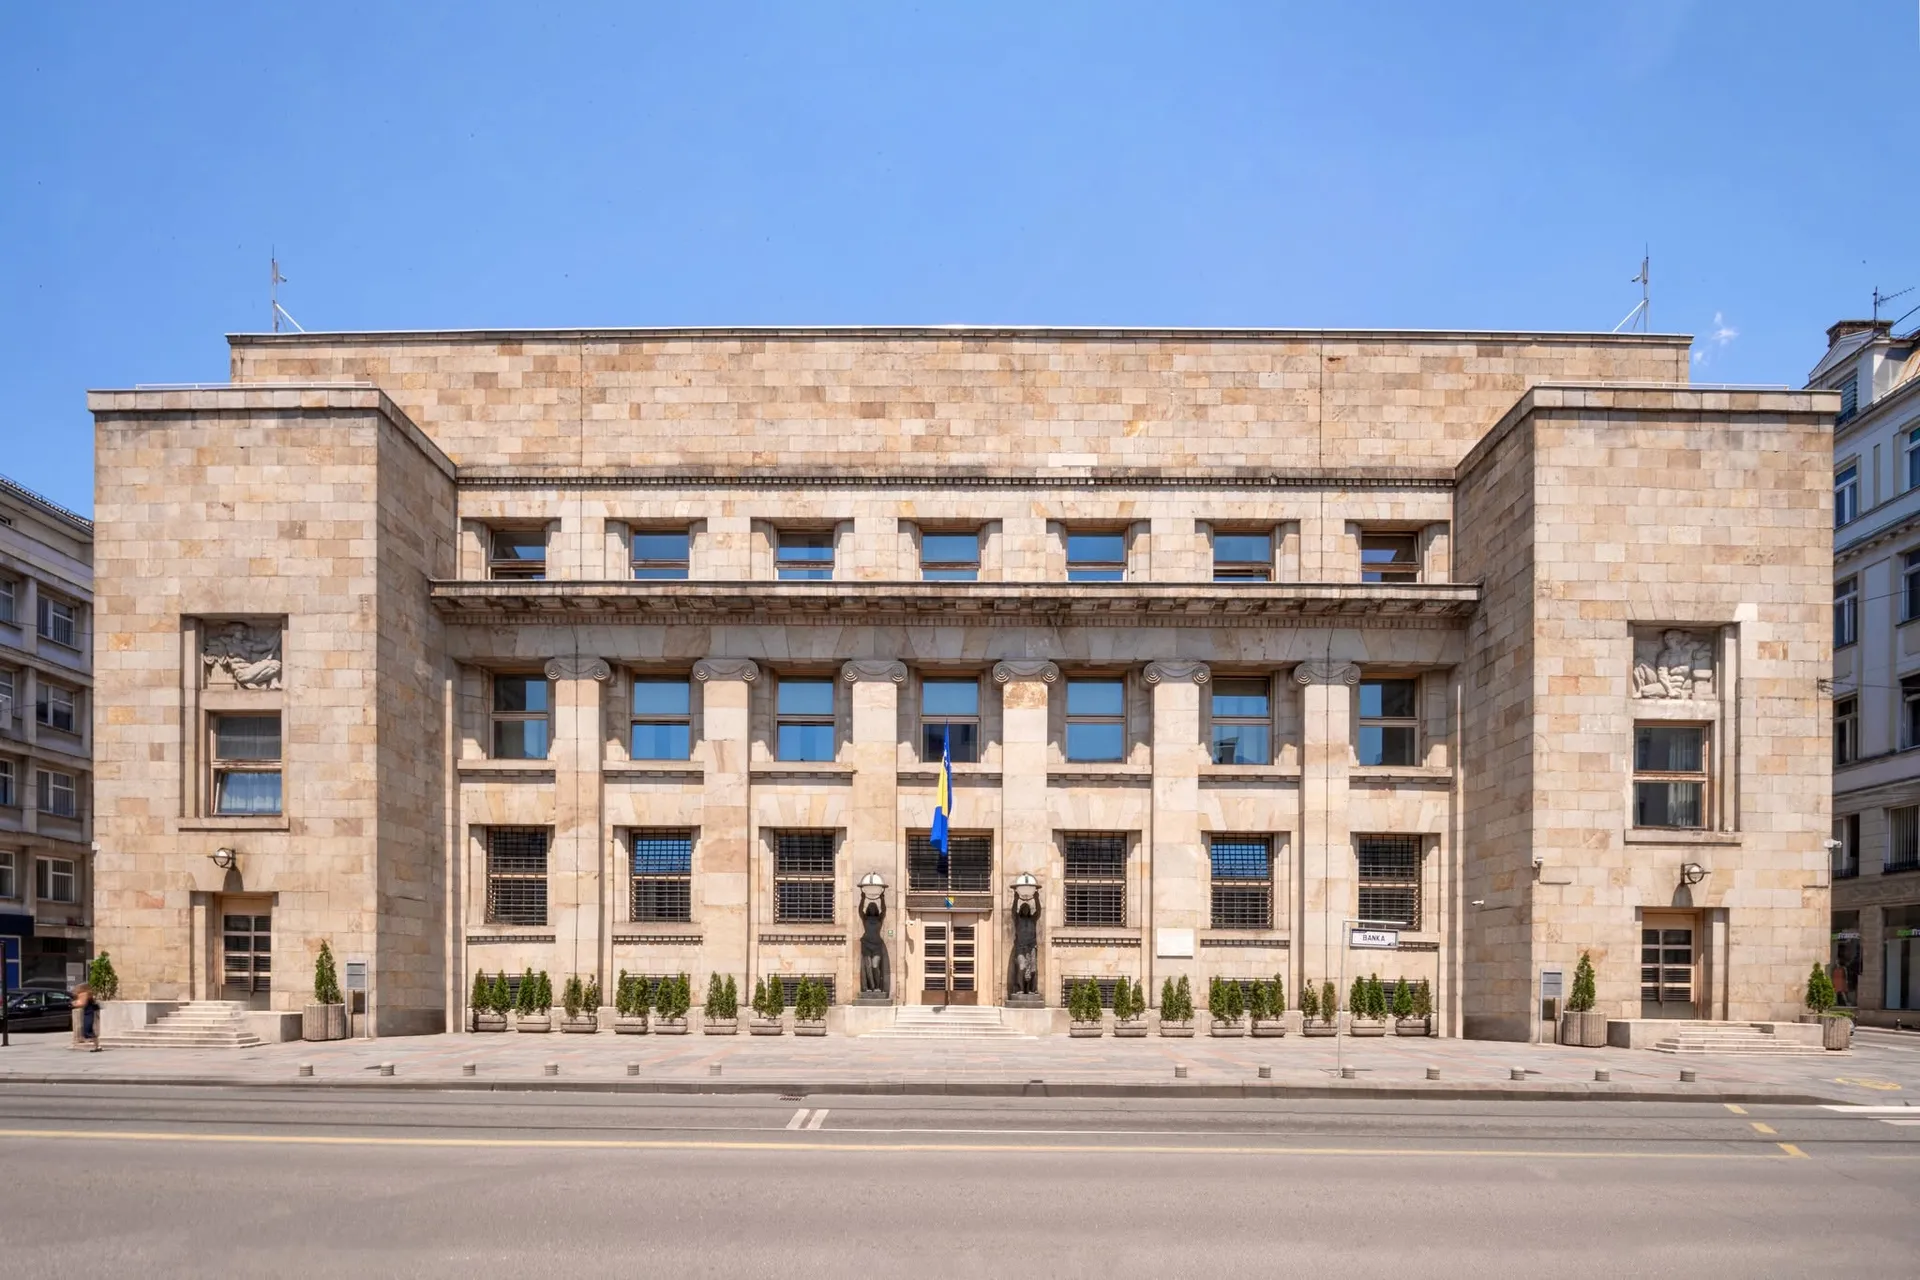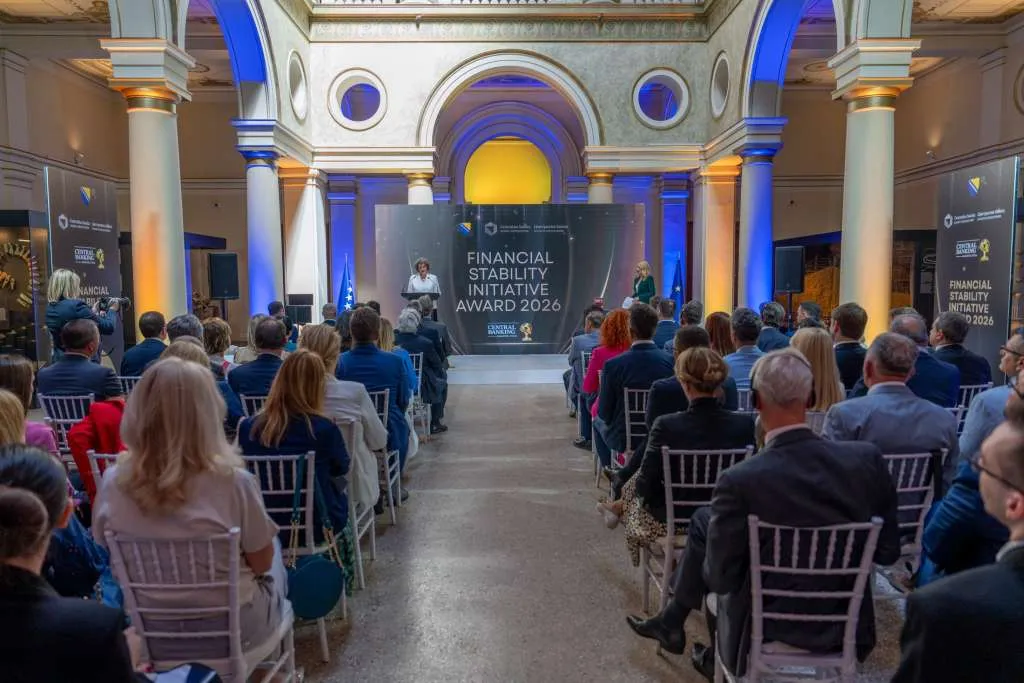

The Central Bank of Bosnia and Herzegovina (CBBH) is the first institution to start conducting stress tests in the financial system of BiH and the only institution conducting stress tests for the banking sector in BiH. The process of developing stress tests was formalized in 2013 with the signing of the document "Guidelines for the Development of Stress Tests and the Use of Prudential Instruments in the CBBH, the Banking Agency of the Federation of BiH (FBA), and the Banking Agency of the Republika Srpska (ABRS)" by these three institutions, reports the BiH news agency Patria.
Stress tests at the CBBH were first conducted in 2007, using scenarios from the IMF's Financial Sector Assessment Program (FSAP) mission from 2006. The scenarios and aggregated results of the stress tests were published in the 2007 Financial Stability Report (FSR). Following the IMF Technical Mission in April 2009, the methodology was changed and new scenarios for stress tests were created, which were used for the 2008 stress tests and presented in the 2008 FSR. The third (current) generation of "top-down" stress tests based on macroeconomic assumptions came into effect after the regional stress testing in the autumn of 2009, conducted by the IMF in cooperation with the World Bank. The frequency of stress test development was changed from annual to quarterly, so the CBBH has been continuously conducting stress tests on a quarterly basis since the second quarter of 2010. Quarterly stress tests are conducted for two years in advance, with special adjustments made for stress tests conducted on a quarterly data basis during the year.
Stress testing is conducted for all commercial banks in the banking system. The data used for stress tests include balance sheet data, income statement data, capital adequacy data, data on the sectoral structure of loans by credit portfolio quality categories, data on provisions by sectors and credit portfolio quality categories, and other prudential data. The main results of stress tests are manifested in the form of recapitalization needs. The assumptions used for developing stress tests can be classified into five groups: macroeconomic variable assumptions (GDP growth, inflation), credit growth assumptions, non-performing loan (NPL) growth assumptions, entity government debt growth assumptions, and interest rate assumptions (active and passive interest rates). The assumptions that most influence the results of stress tests are credit growth and NPL growth, which is implicitly derived from GDP trends. The assumptions proposed by the CBBH are calibrated in cooperation with banking agencies, especially assumptions about credit growth, asset growth, NPL growth, and interest rates. The same assumptions apply to all banks in the system.
Stress tests are conducted under two scenarios: a baseline scenario and an extreme scenario. The baseline scenario is based on projections of key macroeconomic variables and expected reactions of the banking sector to changes in the macroeconomic environment. The extreme scenario assumes a series of low-probability but high-impact negative events for the financial system in BiH. The focus is on credit risk, as the dominant risk in the BiH banking sector. Interest rate risk is also included in the stress tests as an indirect risk that manifests as increased credit risk. The starting assumption in the stress test is that direct credit risk is a consequence of the slowdown in economic activity domestically and abroad, while indirect credit risk is a consequence of changes in interest rates. The stress test scenarios are divided into two shocks: Shock A assumes an increase in NPLs due to a slowdown in economic activity, and Shock B assumes an increase in NPLs due to rising interest rates. The basis of the model is the income statement projection, through which changes in the capital of individual banks are determined to calculate the capital adequacy ratio (CAR). The growth of NPLs, i.e., the transmission of negative real sector trends to the asset quality of the banking sector, occurs in several steps within the model: projected NPL growth is distributed proportionally to the individual bank's share in a specific industry; for the newly obtained NPL level, provisions for credit losses are determined according to the average provisioning for each category, and the amount is compared to the existing provisioning level at the beginning of the period. The determined difference is the effect on the income statement in terms of provisions that need to be made for credit losses and represents the most significant item that can be projected, taking into account the specifics of the BiH banking system. The calculated effects on the numerator and denominator of the capital adequacy ratio (regulatory capital and total risk-weighted assets) are compared to the minimum adequacy ratio prescribed by the regulator (12%), thus calculating the recapitalization needs of individual banks. Upon completion of the stress testing, the results are submitted and discussed with the entity banking agencies.
Banking agencies use the results of stress testing as an additional tool for assessing risks in banks and present them to banks that show weaknesses during testing. Aggregated stress test results are an integral part of the Financial Stability Report. Stress tests represent an exercise of the banking sector's sensitivity to assumed shocks. The results of stress tests should be interpreted in terms of systemic risks, not individual banks' recapitalization needs, and do not represent the sole and sufficient instrument based on whose results, without any additional analysis, individual banks should be ordered to recapitalize.
Komentari (0)
Prijavite se za komentiranje
PrijavaJos nema komentara. Budite prvi!
Minuta
Sve →Iz drugih kategorija
High Representative Not Elected: Germans, French and British Sabotaged Americans, New Attempt at End of June
ČOVIĆ WITHOUT MERCY: How Those Who Brought Ademović to Office Created a Political Hell for Him
Sunny Saturday, quite warm
Tragedy in Albanian resort: Two minors drown